Does a Higher Deductible Lower Homeowners Insurance?
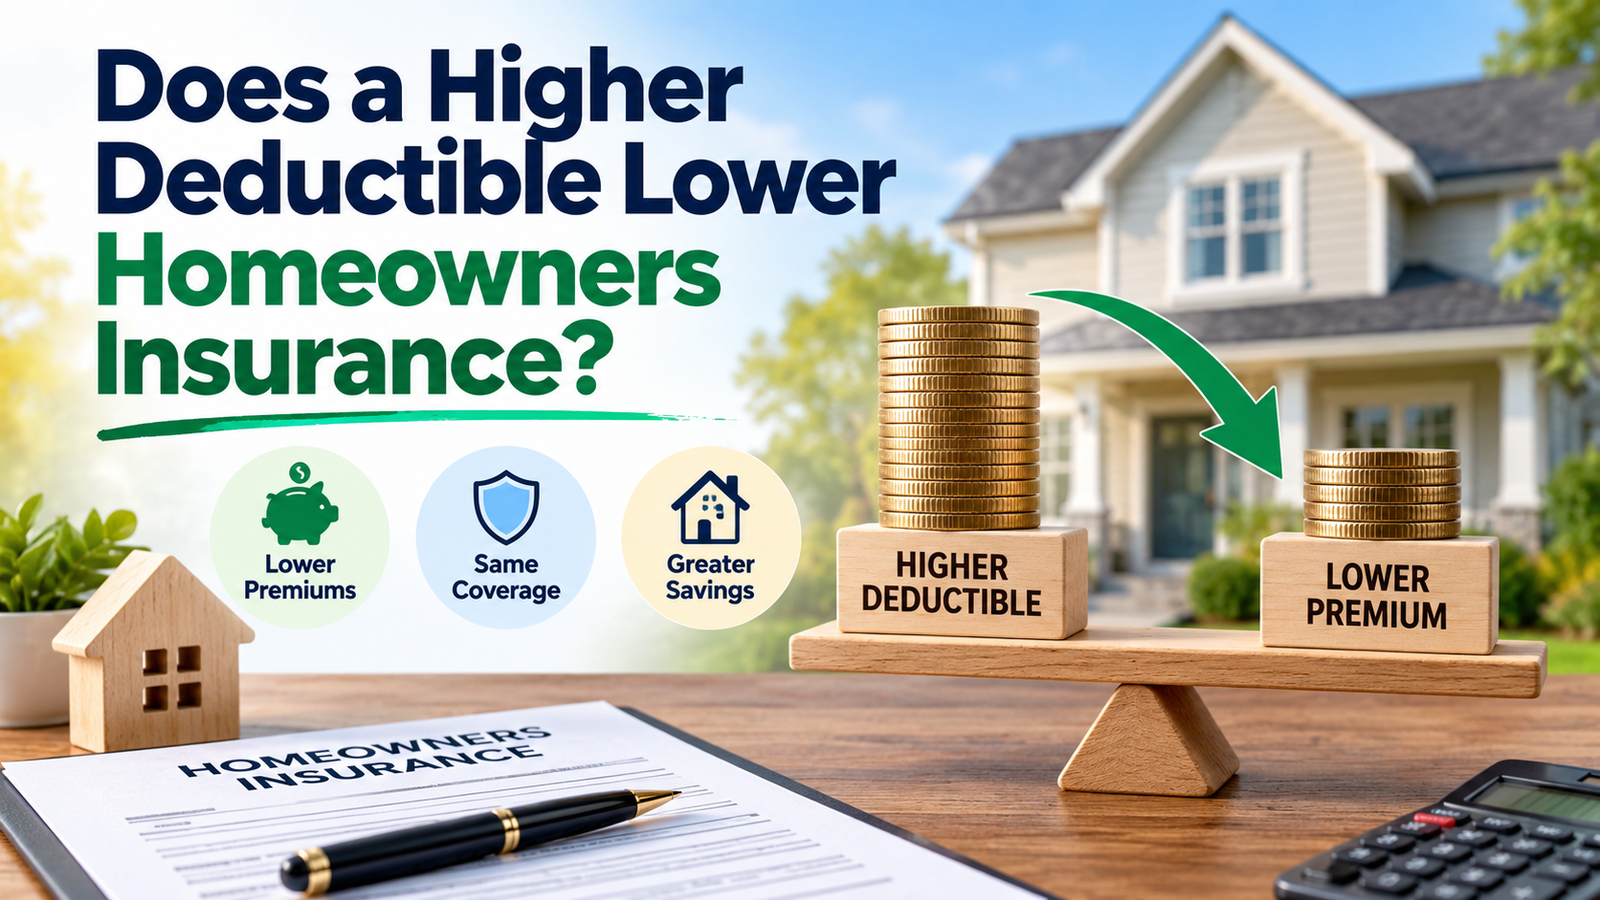
Yes. Choosing a higher deductible will usually lower your homeowners insurance premium.
The reason is simple: when you increase your deductible, you agree to pay more of a covered loss yourself before your insurance company pays its share. Because the insurer is taking on less of the initial financial risk, it can generally charge you less for the policy.
The National Association of Insurance Commissioners explains that lower deductibles generally result in higher homeowners insurance premiums, while choosing a higher deductible can reduce the price you pay for coverage.
But there is an important tradeoff.
A higher deductible may save you money every year, but it also means more money out of your pocket if you need to file a claim.
So the best deductible is not necessarily the highest one available. It is the highest amount you could comfortably afford after an unexpected loss.
How Much Can a Higher Homeowners Insurance Deductible Save?
The exact savings depend on your state, insurance company, home, coverage limits, and deductible options.
Current 2026 Insurance.com rate data shows that increasing a homeowners insurance deductible from $500 to $2,500 saves about $512 per year on average across the country. The actual savings vary substantially by state and insurer.
NerdWallet’s 2026 analysis reaches a similar conclusion from a different dataset. It estimates that increasing a deductible from $1,000 to $2,500 can reduce homeowners insurance rates by about 9% on average.
Those numbers are useful benchmarks, but they are not guaranteed savings.
Your insurer might offer a large reduction when you move from $500 to $2,500, while another company may offer only a modest discount.
That is why it is worth requesting quotes at several deductible levels before changing your policy.
Homeowners Insurance Cost by Deductible
Here is a simple example using a hypothetical policy.
| Deductible | Example Annual Premium | Your Cost Before Insurance Pays |
|---|---|---|
| $500 | $2,800 | $500 |
| $1,000 | $2,600 | $1,000 |
| $2,000 | $2,350 | $2,000 |
| $2,500 | $2,250 | $2,500 |
| $5,000 | $2,050 | $5,000 |
These are illustrative numbers rather than quotes.
The pattern shows the basic tradeoff:
Higher deductible → lower premium → more financial responsibility when you make a claim.
Current national data shows the same general relationship. Insurance.com’s 2026 averages for a policy with $300,000 in dwelling coverage and $300,000 in liability are about $2,872 per year with a $1,000 deductible compared with approximately $2,621 with a $2,500 deductible.
Why Does a Higher Deductible Lower Homeowners Insurance?
Insurance works by transferring financial risk from you to the insurance company.
With a low deductible, the insurer begins paying sooner after a covered loss.
With a higher deductible, you absorb more of that loss yourself.
For example, imagine your home suffers $12,000 in covered damage.
With a $500 deductible, your insurer would generally calculate the covered claim after subtracting $500.
With a $2,500 deductible, you would be responsible for $2,500 before the insurer’s portion of the covered loss.
Because you take on an additional $2,000 of potential claim cost with the higher deductible, the insurance company can generally charge a lower premium.
Triple-I describes deductibles as a way of sharing risk between the policyholder and insurer and notes that larger deductibles generally result in lower premiums.
$500 vs. $1,000 Homeowners Insurance Deductible
A $500 deductible provides lower out-of-pocket exposure after a covered claim.
If your covered damage is $10,000:
$500 deductible: You are responsible for $500.
$1,000 deductible: You are responsible for $1,000.
The $1,000 deductible will commonly have a lower annual premium.
For a homeowner with enough emergency savings to comfortably pay $1,000, accepting the higher deductible may make financial sense.
But the premium reduction matters.
If your insurer saves you only $30 per year for taking on an extra $500 of risk, the change may be less attractive.
If it saves $200 or $300 per year, the decision looks very different.
Always ask your insurer for the actual premium at both deductible levels rather than assuming a certain percentage discount.
$1,000 vs. $2,500 Homeowners Insurance Deductible
This is another common comparison.
Moving from $1,000 to $2,500 means accepting an additional $1,500 of out-of-pocket exposure after a covered property claim.
In exchange, your annual premium will usually decrease.
Current NerdWallet data suggests the average savings from moving from a $1,000 deductible to $2,500 is approximately 9%, although individual results vary.
The important question is whether the premium savings justify taking on an extra $1,500 of risk.
For example:
If the change saves you $300 per year, it would take about five claim-free years for the accumulated premium savings to equal that extra $1,500 of deductible exposure.
That does not mean you should automatically choose one option or the other. It simply gives you a useful way to evaluate the tradeoff.
$500 vs. $2,500 Deductible: How Much Can You Save?
This is where the difference can become more noticeable.
Insurance.com’s current analysis estimates that homeowners save approximately $512 per year on average by raising the deductible from $500 to $2,500.
But location can dramatically change the savings.
In the same dataset, Oklahoma homeowners can save around $1,228 per year on average by making this deductible change, while the estimated savings in Maryland are much smaller.
This is why a national percentage should never be treated as your guaranteed discount.
Ask your insurer:
“What would my exact annual premium be with a $500, $1,000, $2,500, and $5,000 deductible?”
That gives you real numbers for your own property.
What Is a Good Deductible for Homeowners Insurance?
There is no single best homeowners insurance deductible.
Common dollar deductibles include:
- $500
- $1,000
- $2,000
- $2,500
- $5,000
The best option depends largely on your financial situation.
A homeowner with substantial emergency savings may be comfortable carrying a $2,500 or $5,000 deductible in exchange for a lower annual premium.
Someone with limited cash reserves may prefer paying a higher premium for a $500 or $1,000 deductible.
The NAIC recommends choosing a deductible you can realistically afford if you experience a loss.
When Does Raising Your Deductible Make Sense?
A higher deductible may be worth considering when you have enough savings to comfortably pay it, want to reduce your recurring insurance cost, rarely file small property claims, and receive a meaningful premium reduction from your insurer.
For example, suppose your current policy has:
$500 deductible
$3,200 annual premium
Your insurer offers:
$2,500 deductible
$2,650 annual premium
That represents $550 in annual savings.
If you have a strong emergency fund and could comfortably handle the additional $2,000 after a claim, the higher deductible might be reasonable.
But if paying $2,500 unexpectedly would require borrowing money or carrying credit-card debt, the lower premium may not be worth the risk.
When Should You Keep a Lower Deductible?
A lower deductible may be more appropriate if paying a large deductible would create financial hardship.
Remember that homeowners claims are rarely planned.
You could experience:
- Fire damage
- Burst plumbing
- Theft
- Tree damage
- Wind damage
- Hail damage
- Other covered property losses
If a claim happens tomorrow, you need to be able to handle the deductible then—not several months later.
That is why choosing a $5,000 deductible simply because it produces the lowest premium can be risky.
Your insurance should remain financially usable when you actually need it.
How to Calculate Whether a Higher Deductible Is Worth It
A simple calculation can help.
Use:
Additional Deductible Risk ÷ Annual Premium Savings = Break-Even Years
Suppose you are comparing:
Current deductible: $1,000
New deductible: $2,500
Additional risk: $1,500
Annual premium savings: $300
Calculation:
$1,500 ÷ $300 = 5 years
If you go five years without a deductible-triggering claim, your accumulated premium savings would equal the additional $1,500 deductible exposure.
Now consider another example.
Current deductible: $500
New deductible: $2,500
Additional risk: $2,000
Annual savings: $600
$2,000 ÷ $600 = 3.3 years
This does not predict whether you will have a claim. It simply helps you understand the financial tradeoff.
Do Deductibles Apply to Every Homeowners Insurance Claim?
Not necessarily.
A standard property deductible generally applies to covered damage to your home or belongings.
Deductibles typically do not work the same way for homeowners liability claims. Triple-I notes that property-damage claims generally involve a deductible while liability coverage usually does not.
Your policy may also contain multiple deductibles.
This becomes especially important in states exposed to hurricanes, windstorms,s or hail.
Watch for Percentage Deductibles
Not every homeowners insurance deductible is a fixed dollar amount.
Policies in catastrophe-prone areas may have separate deductibles for:
- Hurricanes
- Named storms
- Wind
- Hail
- Earthquakes
These may be expressed as a percentage of your dwelling coverage.
For example, suppose your home has $400,000 in dwelling coverage.
A 2% wind deductible would equal:
$400,000 × 2% = $8,000
That is dramatically different from a standard $1,000 deductible.
The NAIC advises homeowners to check whether named-storm deductibles apply per event, season,n or calendar year because policy rules can differ.
Before increasing your standard deductible, review every deductible in the policy.
Does Increasing Your Deductible Reduce Your Coverage?
Not exactly.
Increasing your deductible does not automatically lower your dwelling coverage limit.
Instead, it changes how much of a covered property loss you are responsible for paying.
For example, a policy could still provide $400,000 in dwelling coverage whether your deductible is $1,000 or $2,500.
What changes is the amount deducted from an eligible claim.
This distinction matters because some homeowners try to save money by reducing their dwelling coverage instead.
That can create underinsurance.
If you are looking for ways to lower your premium, increasing a deductible you can afford may be safer than cutting essential rebuilding coverage simply to reduce the price.
Should You Raise Your Deductible Instead of Reducing Coverage?
Often, this is worth considering.
Your dwelling coverage is designed to provide money to repair or rebuild your house after a covered loss.
Reducing that limit too aggressively could leave you without enough protection after a major disaster.
A deductible changes how much you contribute to a claim, while the coverage limit determines how much insurance protection is available.
Those are very different decisions.
Before cutting coverage, first consider:
- Comparing insurance companies
- Raising your deductible
- Bundling home and auto insurance
- Asking about home-security discounts
- Improving the roof or other risk-mitigation features
- Reviewing optional endorsements
Triple-I and the NAIC both identify a higher deductible as one potential way to reduce homeowners insurance premiums.
Is a $5,000 Homeowners Insurance Deductible Too High?
For some homeowners, yes.
For others, no.
The right answer depends on your savings and the premium reduction you receive.
If you keep $30,000 in emergency savings and a $5,000 deductible reduces your annual premium substantially, the additional risk might be manageable.
If your available emergency cash is only $1,500, a $5,000 deductible could create serious problems after a claim.
Do not choose a deductible based only on the premium.
Choose it based on both:
Annual savings
and
Your ability to pay after a loss
Can Your Mortgage Lender Limit Your Deductible?
Potentially.
Mortgage lenders have an interest in protecting the property securing the loan and may place requirements on homeowners insurance.
Bankrate notes that some lenders may impose limits on the maximum deductible allowed under mortgage terms.
If you have a mortgage and are considering a particularly large deductible, check with your lender or review your mortgage insurance requirements before changing the policy.
Should You File Small Claims With a High Deductible?
A high deductible naturally makes smaller losses less likely to produce an insurance payment.
For example, if you have a $2,500 deductible and experience $2,000 in covered damage, the loss would generally fall below the deductible.
Even when damage slightly exceeds the deductible, some homeowners may decide to pay for a relatively small repair themselves.
Claims history can affect insurance pricing and eligibility depending on the insurer and state, so homeowners should consider both the amount of the potential claim payment and their policy circumstances before filing.
Higher Deductible vs. Lower Deductible
Here is the simplest way to compare the two choices:
| Higher Deductible | Lower Deductible |
|---|---|
| Lower premium | Higher premium |
| Higher out-of-pocket claim cost | Lower out-of-pocket claim cost |
| More financial risk retained by you | More risk transferred to insurer |
| Better suited to stronger emergency savings | May suit homeowners with limited cash reserves |
| Can produce meaningful long-term savings | Provides easier-to-manage claim costs |
Neither option is automatically better.
The correct choice depends on your finances and the actual premium difference your insurer offers.
Frequently Asked Questions
Does a higher deductible always lower homeowners insurance?
Usually, but not necessarily by the same amount with every insurer. The NAIC states that choosing a higher deductible reduces homeowners insurance pricing in general, but the actual savings depend on the company and policy.
How much can I save by raising my homeowners insurance deductible?
Current Insurance.com data estimates an average savings of around $512 per year when moving from a $500 deductible to $2,500, although savings vary significantly by state and insurer.
Is a $1,000 deductible good for homeowners insurance?
A $1,000 deductible is common and may provide a reasonable balance between premium cost and out-of-pocket exposure for many homeowners. Whether it is right for you depends on your savings and the other deductible options available.
Is a $2,500 homeowners deductible too high?
Not necessarily. If you could comfortably pay $2,500 immediately after a covered loss and the premium savings are meaningful, it may be reasonable. If paying $2,500 would cause financial hardship, a lower deductible may be safer.
Does a $5,000 deductible lower homeowners insurance more?
Usually, a $5,000 deductible will cost less than a lower deductible on an otherwise comparable policy, but savings do not always increase proportionally. Insurance.com notes that some insurers see the most meaningful premium reduction when moving into roughly the $2,000–$2,500 range.
Is a higher deductible better for homeowners insurance?
It is better only if the premium savings are worthwhile and you can comfortably pay the deductible after a loss.
Does the deductible affect liability coverage?
Homeowners property deductibles generally apply to covered property losses rather than personal liability claims.
Can I change my homeowners insurance deductible?
Insurance companies generally offer multiple deductible options, although available amounts vary by insurer and location. Ask your insurer what deductible choices are available and how each would change your premium.
Bottom Line: Does a Higher Deductible Lower Homeowners Insurance?
Yes. A higher homeowners insurance deductible will usually lower your premium.
The NAIC, Tripl,e,-I and current insurance rate studies all support that basic relationship: when you take responsibility for more of a potential loss, the insurer generally charges less for the policy.
But the biggest deductible is not automatically the smartest choice.
Compare the premium at several deductible levels.
Calculate how much you would actually save each year.
Then ask yourself one important question:
Could I comfortably pay this deductible tomorrow if something happened to my home?
If the answer is yes and the premium savings are meaningful, increasing your deductible may be an effective way to lower your homeowners insurance cost.
If the answer is no, keeping a somewhat higher premium and a more manageable deductible may provide better financial protection.
Editorial Disclaimer
This article is provided for general educational and informational purposes and is not personalized insurance, legal,egal or financial advice. Deductible options, premium savings, policy terms, a nd claim settlement rules vary by insurer, state and individual policy. Review your declarations page and policy documents and contact your insurer or a properly licensed insurance professional before changing your deductible.